<br><div data-attribute="article-content-body">
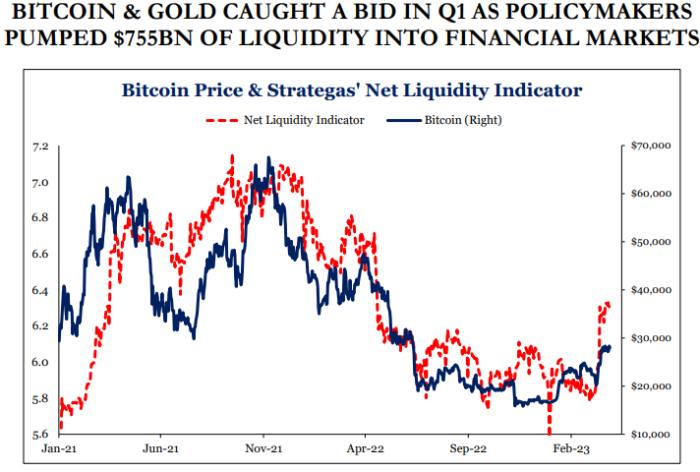
<experimental><div class="n-content-layout" data-layout-name="card" data-layout-width="fullWidth"><div class="n-content-layout__container"><div class="n-content-layout__slot" data-slot-width="true"><p>This text is an on-site model of our Unhedged publication. Enroll <a target="_blank" href="https://ep.ft.com/newsletters/subscribe?newsletterIds=584573e552860d000491cdb8" data-trackable="link" rel="noopener">here</a> to get the publication despatched straight to your inbox each weekday</p></div></div></div></experimental><p>Good morning. Right here at Unhedged our predominant undertaking for the remainder of this week is ignoring the indictment of a second-tier actual property developer from Florida. However that ought to go away us with just a few different issues to jot down about. Electronic mail us your concepts: robert.armstrong@ft.com and ethan.wu@ft.com. </p><h2 id="opec-flexes-markets-unimpressed-0" class="n-content-heading-2">Opec flexes, markets unimpressed</h2><p>Oil rose greater than 6 per cent, to $85, yesterday. This was in response Opec’s announcement, over the weekend, that Saudi Arabia would <a target="_blank" href="https://www.ft.com/content/c95db701-5d1d-4020-a897-9b47085eef96" data-trackable="link" rel="noopener">cut</a> its manufacturing by 5 per cent, and that members of the Opec+ cartel would comply with with cuts of their very own. The transfer was wealthy with political implications. Many analysts argue it marks a strategic change by the Saudis and their allies, fairly than a tactical transfer to defend a weak oil worth. From <a target="_blank" href="https://www.ft.com/content/3cc7ced1-70db-4854-bd61-d9c92a9c7710" data-trackable="link" rel="noopener">the FT</a>:</p><blockquote class="n-content-blockquote"><p>“It’s a Saudi-first coverage. They’re making new pals, as we noticed with China,” [Helima Croft, of RBC Capital Markets] mentioned, referring to a current Beijing-brokered diplomatic deal between Saudi Arabia and Iran. The dominion was sending a message to the US that “it’s not a unipolar world”.</p></blockquote><p>This feels like severe stuff to us. So we had been struck by how little markets responded on Monday. Shares leveraged to grease, from upstream manufacturing to oilfield providers, popped. However provided that sustained greater oil costs are stagflationary, we had been a bit stunned to see positive aspects throughout a wide range of different sectors (healthcare, supplies, staples). Extra stunning nonetheless, the policy-sensitive two-year bond yield fell 9 foundation factors. </p><p>That is significantly notable provided that Opec+ has a traditionally excessive degree of management over oil costs proper now, as Goldman Sachs’s Daan Struyven has argued. The addition of the “+” international locations (Russia, Kazakhstan, Mexico et al) to the cartel have elevated its market share. Larger monetary self-discipline from non-Opec producers, significantly the US, has decreased the value elasticity of world provide. And international demand has develop into extra inelastic as a result of (amongst different causes) transportation gas, which has few substitutes, now makes up a higher share of complete demand. If Opec+ needs play for sustained greater oil costs, it's holding good playing cards.</p><p>Moreover, as our colleague Derek Brower of <a target="_blank" href="https://www.ft.com/energy-source" data-trackable="link" rel="noopener">FT Energy Source</a> identified to us, many analysts had been already declaring that oil was positioned for a rally within the second half of 2023, as resurgent demand from China pushed the market into deficit. Struyven, for instance, has been saying for months that oil would move $100 by year-end. </p><p>Even when greater oil shouldn't be sufficient to vary the expansion outlook materially, we'd anticipate some fear concerning the inflationary results, given the market’s monomaniacal give attention to Federal Reserve coverage. Power is 7 per cent of CPI, and has a strong influence even on core (ex-food and power) CPI by transportation providers, which has been an important swing issue within the inflation measures the Fed cares about most.</p><p>So why the indifference? As soon as once more, it appears to be like to us just like the comfortable touchdown situation is exercising a hypnotic impact available on the market. If you happen to assume there's a actual menace the economic system will hold working too sizzling, the extra inflationary results of excessive oil costs are an unwelcome extra danger. If you happen to assume the central forecast is for demand softening sufficient to deliver down inflation, then sustained greater oil costs don’t appear that a lot of a menace.</p><p>For instance, right here is Capital Economics’ Adam Hoyes:</p><blockquote class="n-content-blockquote"><p>The [initial] strikes within the bond market [with inflation breakevens rising following the Opec + announcement] have greater than reversed because the launch of the March ISM Manufacturing survey, the place the headline index slumped to a brand new cyclical low and different indices pointed to an additional easing in worth pressures. We wouldn’t be stunned if this sample — greater oil costs however decrease Treasury yields — continued over the remainder of this 12 months, although they’ve typically moved collectively. Admittedly, we do assume oil demand is ready to be weak over the remainder of this 12 months, with development in lots of main economies prone to be sluggish at greatest.</p></blockquote><p>Hoyes, and varied different analysts who struck related notes, might very properly be proper. Our level is simply that there's a part of the chance distribution (20 per cent of it?) the place the labour market stays too tight, and economic system doesn't cool materially, and the Fed has to maintain charges excessive. In that tail of the curve, greater oil costs might be an actual drawback.</p><h2 id="bitcoins-new-old-narrative-1" class="n-content-heading-2">Bitcoin’s new previous narrative</h2><p>Bitcoin’s 70 per cent ascent this 12 months occurred in two phases. The primary was the <a target="_blank" href="https://www.ft.com/content/f5a3a39f-d079-4b54-a3b8-b874c628f386" data-trackable="link" rel="noopener">flight-to-shite</a> that started the 12 months, as goals of a comfortable touchdown and decrease rates of interest set off a rally in all method of high-duration junk. The second was the fallout from Silicon Valley Financial institution’s collapse. As bond yields fell, bitcoin’s worth popped. Flows into crypto funding merchandise are at their highest since mid-2022, in response to <a target="_blank" href="https://blog.coinshares.com/volume-124-digital-asset-fund-flows-weekly-report-85c669f9a6d8" rel="noreferrer noopener" data-trackable="link">CoinShares</a>. </p><p>After a run of <a target="_blank" href="https://www.ft.com/content/5514db89-0a5b-4725-99ec-8d53b42cea81" data-trackable="link" rel="noopener">eerily stable</a> worth motion within the second half of final 12 months, this can be a massive change. A rally amid a banking panic is catnip for bitcoiners. And the brand new crypto story is identical previous crypto story: individuals are quick dropping confidence in banks and are flocking to bitcoin.</p><p>Right here, for instance, is Balaji Srinivasan, previously a prime determine at Coinbase and Andreesen Horowitz, <a target="_blank" href="https://twitter.com/balajis/status/1636822077775941633?s=20" rel="noreferrer noopener" data-trackable="link">spinning a yarn</a> final month about why a “stealth monetary disaster” is poised to result in hyperinflation and mass bitcoin adoption. He claims to have wager $1mn this can occur by June:</p><blockquote class="n-content-blockquote"><p>The central banks, the banks, and the banking regulators all knew an enormous crash was coming — the phrase is “unrealised losses”. However they by no means notified you, the depositor . . . </p><p>It’s Uncle Sam Bankman-Fried. Similar to SBF used your deposits to purchase shitcoins, utilizing accounting tips to idiot himself and others into utilizing the cash, so too did the banks . . . </p><p>All of them used the deposits to purchase the last word shitcoin: long-dated US Treasuries. And so they all obtained [wrecked] on the identical time, in the identical means, as a result of they purchased the identical asset from the identical vendor who devalued it on the identical time: the Fed . . . </p><p>So anybody who wager on long-term Treasuries obtained killed in 2021. And now, anybody who bets on short-term Treasuries goes to get killed in 2023. Absolutely the worst place you might be is to have massive quantities of belongings locked up in three-month treasury payments. The ~5 per cent rate of interest supplied by massive banks (G-SIBs) is a lure. Most fiat financial institution accounts at the moment are a lure, for these international locations whose central bankers adopted the Fed . . . </p><p>That is the second that the world redenominates on Bitcoin as digital gold, returning to a mannequin very similar to earlier than the twentieth century.</p></blockquote><p>This can be a bit loony (what's the worst-case situation for three-month Treasuries yielding 4.6 per cent?), although first chunk of Srinivasan’s story is legible. Whether or not banks ought to’ve accounted for mark-to-market losses on long-dated securities is a <a target="_blank" href="https://www.ft.com/content/e54c7e90-e234-4c76-a4fd-55336c6dfbea" data-trackable="link" rel="noopener">live debate</a>. However we are able to’t make the leap from “long-term Treasuries obtained killed” to “the world is about to drop fiat foreign money”. </p><p>There’s a extra credible story for bitcoin’s bumper quarter: liquidity. Daniel Clifton at Strategas calculates that US policymakers, on web, injected $755bn in liquidity within the first quarter of this 12 months, whereas they had been web subtracters of liquidity all by final 12 months. The correlation between adjustments in liquidity and bitcoin’s worth appears to be like tight:</p> <figure class="n-content-image n-content-image--full" style="width: 700px; max-width: 100%;"> <picture><source srcset="https://www.ft.com/__origami/service/image/v2/images/raw/https%3A%2F%2Fd1e00ek4ebabms.cloudfront.net%2Fproduction%2F38bed8d6-edbe-47a3-9b38-91a488b22393.png?dpr=1&fit=scale-down&source=next&width=700 1x" media="(min-width: 1220px)"> <source srcset="https://www.ft.com/__origami/service/image/v2/images/raw/https%3A%2F%2Fd1e00ek4ebabms.cloudfront.net%2Fproduction%2F38bed8d6-edbe-47a3-9b38-91a488b22393.png?dpr=1&fit=scale-down&source=next&width=540 1x" media="(min-width: 980px) and (max-width: 1219px)"> <source srcset="https://www.ft.com/__origami/service/image/v2/images/raw/https%3A%2F%2Fd1e00ek4ebabms.cloudfront.net%2Fproduction%2F38bed8d6-edbe-47a3-9b38-91a488b22393.png?dpr=1&fit=scale-down&source=next&width=700 1x" media="(min-width:491px) and (max-width: 979px)"> <source srcset="https://www.ft.com/__origami/service/image/v2/images/raw/https%3A%2F%2Fd1e00ek4ebabms.cloudfront.net%2Fproduction%2F38bed8d6-edbe-47a3-9b38-91a488b22393.png?dpr=1&fit=scale-down&source=next&width=490 1x" media="(max-width: 490px)"><img src="https://www.ft.com/__origami/service/image/v2/images/raw/https%3A%2F%2Fd1e00ek4ebabms.cloudfront.net%2Fproduction%2F38bed8d6-edbe-47a3-9b38-91a488b22393.png?fit=scale-down&source=next&width=700" data-id="https://api.ft.com/content/38bed8d6-edbe-47a3-9b38-91a488b22393" data-image-type="image" data-original-image-width="712" data-original-image-height="480" alt="Chart of bitcoin prices"/></source></source></source></source></picture>
</figure> <p>Why ought to liquidity injections assist bitcoin? We appreciated this illustration from Citi strategist Matt King, on Bloomberg’s Odd Tons podcast final week, of how buyers get crowded into riskier belongings:</p><blockquote class="n-content-blockquote"><p>For me, it’s actually about this stability between how a lot cash the non-public sector has relative to what number of belongings can be found to soak up that cash . . . </p><p>You possibly can’t see all these transferring elements, however what I believe goes on is that the man who would’ve purchased payments buys bonds, the man who would’ve purchased bonds buys IG credit score, the man who would’ve purchased IG buys high-yield, and so forth . . . </p><p>The perfect correlations [with central bank liquidity injections] I discover of all are precisely with the preferred belongings like cryptocurrency or Tesla inventory.</p></blockquote><p>On this sense the banking disaster, in forcing a brand new spherical of liquidity help, actually has helped bitcoin past the narrative enhance, although not for the explanations Srinivasan suggests. Systemic stresses carry bitcoin not as a result of they discredit the monetary system, however as a result of the regulatory responses are good for speculators. (<em>Ethan Wu</em>)</p><h2 id="one-good-read-2" class="n-content-heading-2">One good learn</h2><p>Some <a target="_blank" href="https://www.bloomberg.com/news/articles/2023-04-03/black-swans-angry-hedge-funds-and-how-to-make-a-3-612-return" rel="noreferrer noopener" data-trackable="link">fascinating hedge fund sniping</a>: Derek Kaufman (former Citadel), Boaz Weinstein (Saba Capital) and Cliff Asness (AQR) don’t like how Mark Spitznagel (Universa) calculates his returns.</p><experimental><div class="n-content-layout" data-layout-name="card" data-layout-width="fullWidth"><div class="n-content-layout__container"><h2 id="recommended-newsletters-for-you-3" class="n-content-heading-4">Really useful newsletters for you</h2><div class="n-content-layout__slot" data-slot-width="true"><p><strong>Due Diligence</strong> — High tales from the world of company finance. Enroll <a target="_blank" href="https://ep.ft.com/newsletters/subscribe?newsletterIds=58db721900eb6f0004d56a23" data-trackable="link" rel="noopener">here</a></p><p><strong>The Lex Publication</strong> — Lex is the FT’s incisive every day column on funding. Join our publication on native and international tendencies from professional writers in 4 nice monetary centres. Enroll <a target="_blank" href="https://ep.ft.com/newsletters/subscribe?newsletterIds=56657d10e4b04e04251004fd" data-trackable="link" rel="noopener">here</a></p></div></div></div></experimental></div><script async src="//platform.twitter.com/widgets.js" charset="utf-8"></script>